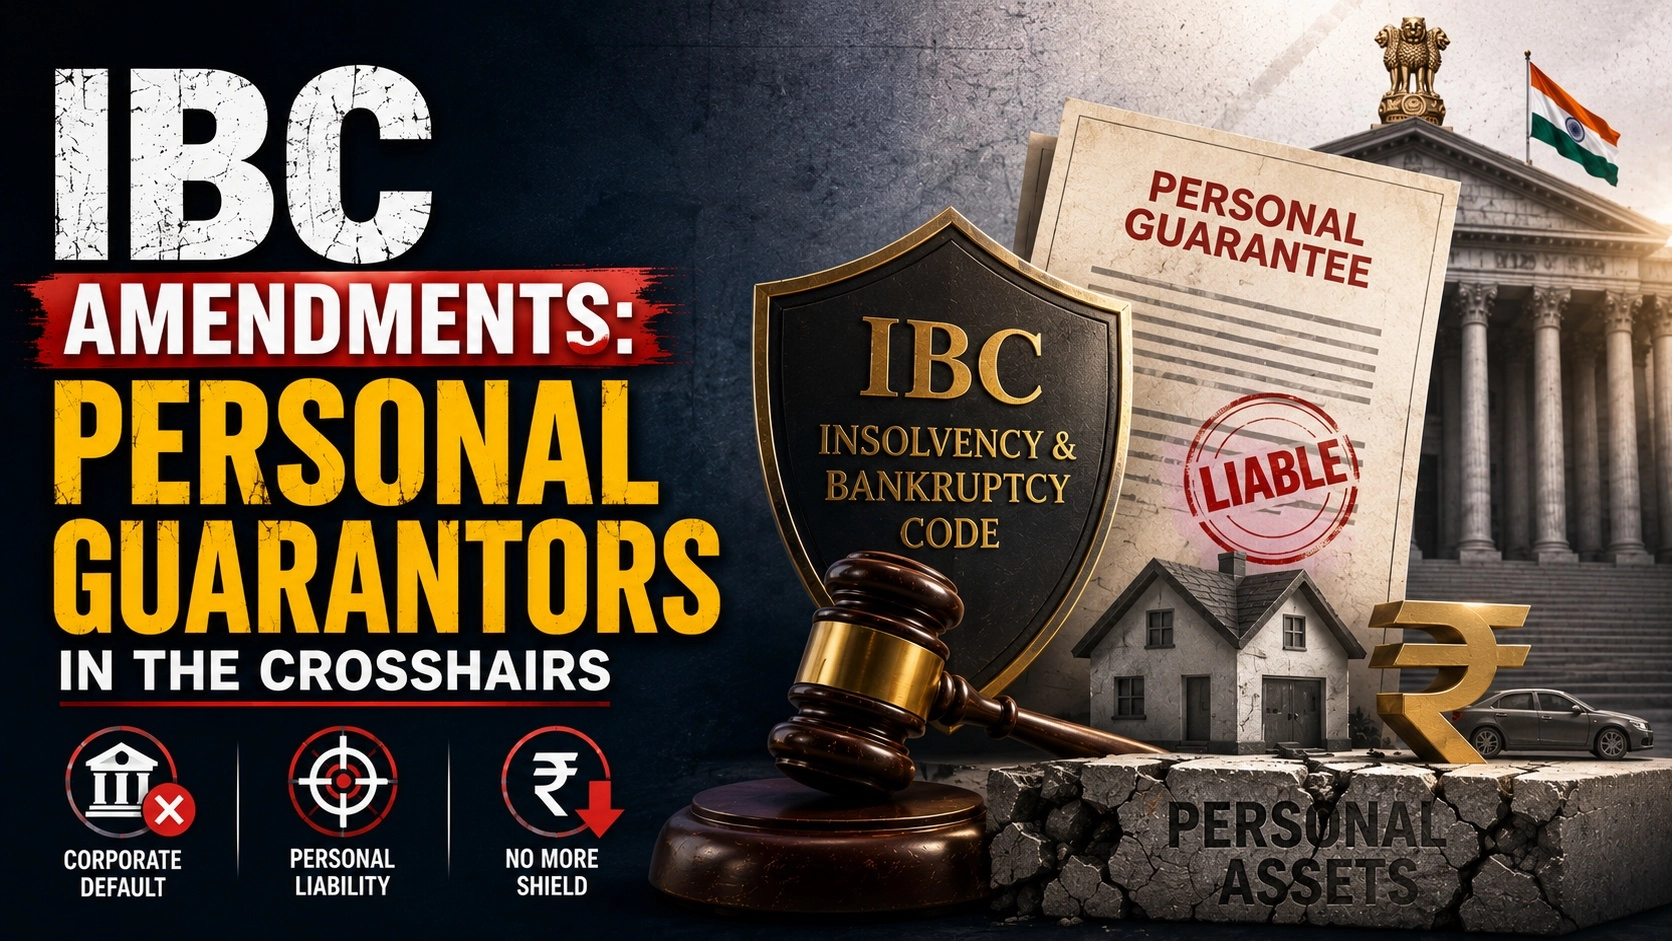
Insolvency and Bankruptcy Code (IBC) Amendments: Personal Guarantors in the Crosshairs
When the Insolvency and Bankruptcy Code (IBC) was enacted, its primary focus was on Corporate Insolvency Resolution Processes (CIRP)—taking control of defaulting companies away from promoters and handing it to creditors. However, a significant legal battle has raged over the fate of the promoters themselves, specifically when they act as personal guarantors for corporate loans.
In Indian corporate lending, it is standard practice for banks to demand personal guarantees from the managing directors or promoters of a company before sanctioning massive corporate loans. For years, promoters believed that if the company defaulted and went into IBC, their personal assets remained shielded. Recent legal amendments and a landmark Supreme Court judgment have shattered this illusion, bringing personal guarantors firmly into the crosshairs of the IBC.
This shift represents one of the most profound expansions of creditor rights in Indian legal history, fundamentally altering the risk calculus for corporate promoters.
The Supreme Court Upholds the Provisions
The controversy centered around a specific government notification that brought Part III of the IBC into effect specifically for personal guarantors to corporate debtors. Promoters challenged this across various High Courts, arguing that initiating insolvency against a personal guarantor while the corporate debtor is already undergoing CIRP amounts to double dipping by the banks.
The Supreme Court of India, in a definitive ruling, upheld the constitutional validity of these provisions. The Court clarified a critical legal principle: the approval of a resolution plan for a corporate debtor does not discharge the personal guarantor of their liability. The liability of the guarantor is co-extensive with that of the principal debtor, but the statutory discharge of the company under the IBC does not equate to a contractual discharge of the guarantor.
The Interim Moratorium: A Procedural Trap?
One of the most heavily litigated aspects of these provisions is the "interim moratorium." Under Section 96 of the IBC, the moment a creditor files an application to initiate insolvency against a personal guarantor, an interim moratorium kicks in automatically.
This means all pending legal actions or proceedings regarding any debt against the guarantor are instantly stayed. Promoters argued that this automatic stay, triggered without giving them an opportunity to be heard (a violation of natural justice), severely restricts their fundamental right to conduct business and manage their personal finances.
| Moratorium Type | Trigger Mechanism | Impact Scope |
|---|---|---|
| Corporate Moratorium (Sec 14) | Triggered only after the Adjudicating Authority admits the CIRP application. | Protects the assets of the company from recovery suits. |
| Personal Guarantor Interim Moratorium (Sec 96) | Triggered automatically upon the mere filing of the application by the creditor. | Freezes the personal debt liabilities and ongoing cases against the individual guarantor. |
The Supreme Court rejected the promoters' arguments, stating that the interim moratorium is primarily meant to protect the guarantor from a multiplicity of proceedings by different creditors while the resolution professional assesses the total debt. The Court held that the right to be heard arises at the later stage when the Adjudicating Authority decides whether to formally admit or reject the application.
The Consequences for Promoters
The legal validation of pursuing personal guarantors has dramatically shifted the balance of power during debt restructuring negotiations. Promoters can no longer threaten to walk away from a struggling company, leaving banks to absorb the losses. If they refuse to cooperate in finding a viable resolution plan for the corporate debtor, banks hold the ultimate leverage: forcing the promoters into personal bankruptcy, jeopardizing their personal wealth, real estate, and future ability to hold directorships.
Moving Forward
The aggressive enforcement of personal guarantees under the IBC is expected to foster a culture of responsible borrowing in India. Promoters are now acutely aware that the corporate veil will not protect their personal mansions if their business empire collapses under a mountain of unpaid debt. As the National Company Law Tribunal (NCLT) begins to process thousands of these personal insolvency applications, the legal contours of wealth protection for India's corporate elite are being permanently redrawn.