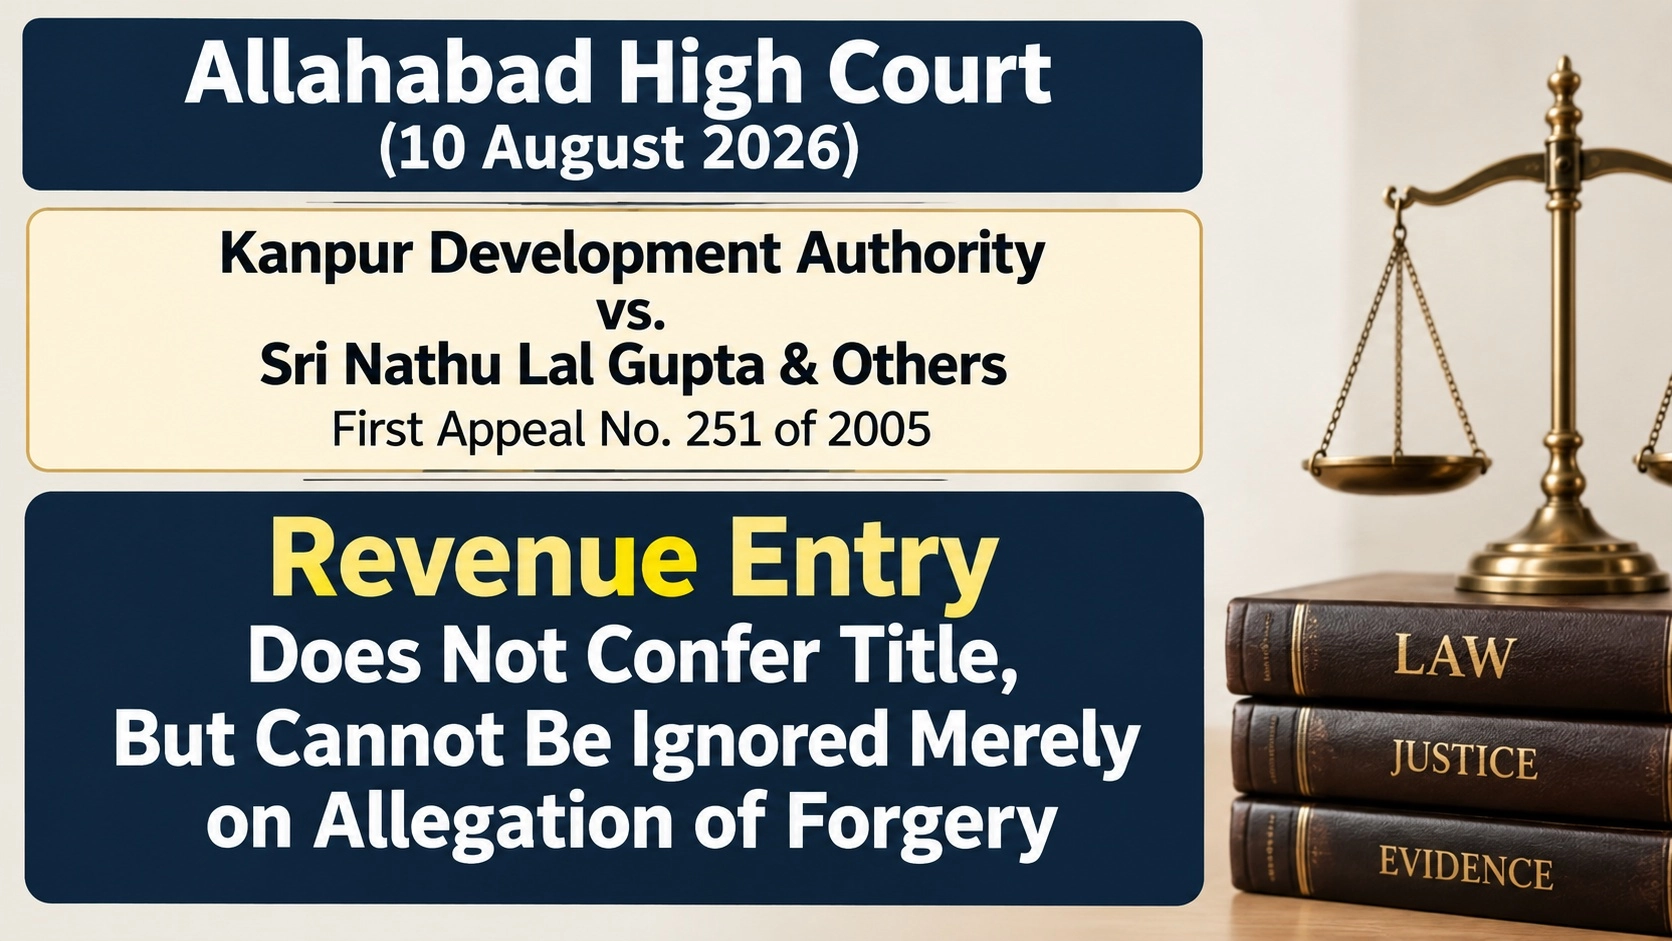
इलाहाबाद हाईकोर्ट ने स्पष्ट किया कि राजस्व अभिलेख (Revenue Entry) अपने आप में स्वामित्व (Title) प्रदान नहीं करता है, लेकिन किसी मौजूदा राजस्व प्रविष्टि को केवल विपक्षी द्वारा फर्जी या कूटरचित होने का आरोप लगाने मात्र से फर्जी नहीं माना जा सकता।
जब तक ऐसी राजस्व प्रविष्टि को सक्षम राजस्व प्राधिकारी या सक्षम न्यायालय द्वारा निरस्त, संशोधित अथवा समाप्त नहीं किया जाता, तब तक उसका कानूनी एवं साक्ष्यात्मक महत्व बना रहता है।
न्यायालय ने यह भी स्पष्ट किया कि “Revenue Entry से Title नहीं बनता” और “मौजूदा Revenue Entry को नजरअंदाज किया जा सकता है”—ये दोनों अलग-अलग बातें हैं। प्रविष्टि की evidentiary value का मूल्यांकन पूरे साक्ष्य के आधार पर किया जाना चाहिए।
साथ ही, स्थायी निषेधाज्ञा (Permanent Injunction) के वाद में प्रत्येक मामले में अलग से स्वामित्व की घोषणा (Declaration of Title) मांगना अनिवार्य नहीं है। यदि वादी अपना कब्जा स्थापित करता है और प्रतिवादी उससे बेहतर अधिकार सिद्ध नहीं कर पाता, तो उपयुक्त परिस्थितियों में केवल injunction की राहत दी जा सकती है।
निर्णय का पैराग्राफ 41
"41. The contention of the appellant that the revenue entry does not by itself confer title is undoubtedly a settled proposition. But that proposition has to be distinguished from the question whether an existing revenue entry can be ignored altogether. A revenue entry may not, by itself, create title, but an existing and unchallenged entry cannot be treated as forged or wiped out from consideration merely on the basis of an allegation made by the opposite party. Its evidentiary value has to be assessed in the context of the entire evidence on record."
मामला: Kanpur Development Authority vs. Sri Nathu Lal Gupta & Others
न्यायालय: इलाहाबाद हाईकोर्ट
पीठ/न्यायाधीश: माननीय न्यायमूर्ति अनिल कुमार-X
वाद संख्या: First Appeal No. 251 of 2005
मूल वाद: O.S. No. 2001 of 1984
आक्षेपित आदेश: 09.11.2004, Additional Civil Judge (Senior Division), Kanpur Nagar
निर्णय/आदेश की तारीख: 10 अगस्त 2026
अपीलकर्ता: Kanpur Development Authority
प्रतिवादी: Sri Nathu Lal Gupta & Others
अंतिम परिणाम: अपील खारिज (Appeal Dismissed) और ट्रायल कोर्ट का निर्णय बरकरार रखा गया।
आदेश का लिंक
https://elegalix.allahabadhighcourt.in/elegalix/WebDownloadJudgmentDocument.do?judgmentID=13486473
No comments yet. Be the first to share your thoughts!